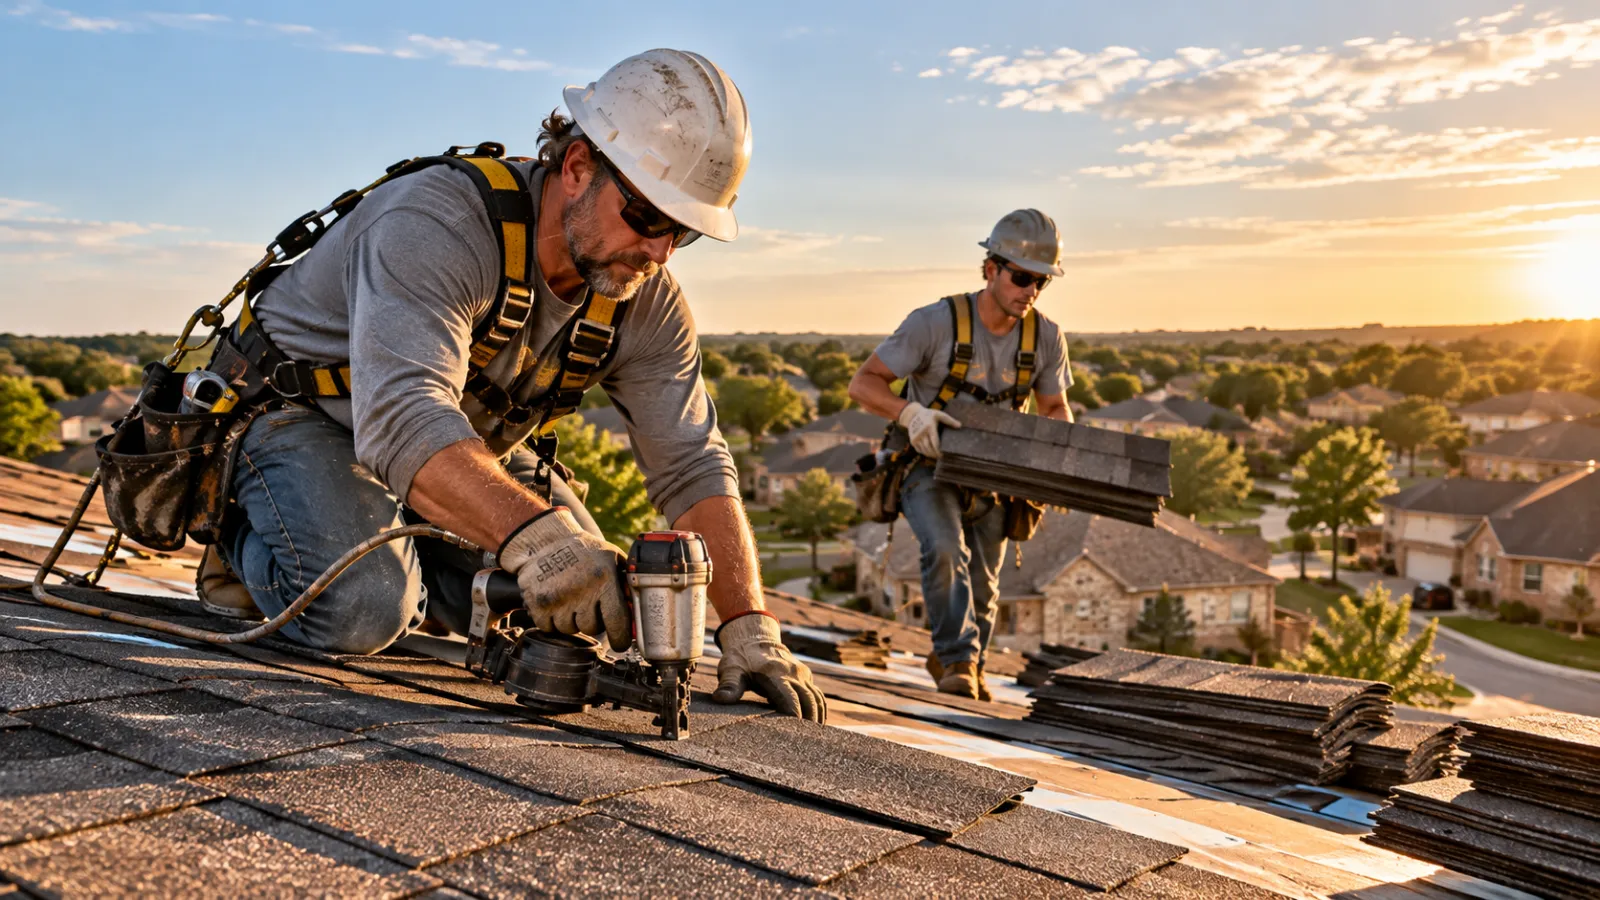
Short Answer: Roofing is one of the highest-risk trades in Texas. Workers’ comp rates for roofers run **$5 to $15 per $100 of payroll**—roughly 3 to 6 times more than office-based businesses. For a roofer earning $50,000 per year, expect to pay $2,500 to $7,500 annually. Texas law doesn’t require most private employers to carry coverage, but the lawsuit exposure for roofing injuries is severe enough that going without is a gamble most roofers shouldn’t take.
Why Roofing Is a High-Risk Classification in Texas
The Texas Department of Insurance classifies roofing as a high-hazard industry. That classification isn’t arbitrary. It reflects real injury data.
Roofers face:
- Falls from height — the leading cause of death in roofing
- Heat-related illness — Texas summers push roof surface temperatures over 150°F
- Struck-by injuries — falling tools, materials, and equipment
- Repetitive strain — kneeling, bending, and lifting all day
- Chemical exposure — roofing adhesives, sealants, and solvents
OSHA ranks roofing among the most dangerous occupations in the United States. Falls alone account for the majority of roofing fatalities.
That risk translates directly to your workers’ comp premium.
Texas Workers Comp Rates for Roofers in 2026
Roofing falls under Texas workers’ comp classification codes for roofing contractors. Rates vary by carrier, but here’s the realistic range:
| Coverage Type | Rate per $100 Payroll |
|---|---|
| Roofing — residential | $5.00 to $10.00 |
| Roofing — commercial | $8.00 to $15.00 |
| Roofing — metal | $6.00 to $12.00 |
Important: These are manual rates before any experience modifier or discounts. Your actual premium depends on your claims history, safety program, and the carrier you choose.
Real Cost Examples
Example 1: Small Residential Roofing Crew
- 3 roofers, $150,000 total payroll
- Rate: $7.00 per $100
- Annual premium: $10,500
Example 2: Solo Roofer with 1 Helper
- 2 workers, $80,000 total payroll
- Rate: $6.50 per $100
- Annual premium: $5,200
Example 3: Commercial Roofing Company
- 8 roofers, $400,000 total payroll
- Rate: $12.00 per $100
- Annual premium: $48,000
Example 4: Small Metal Roofing Business
- 2 roofers, $90,000 total payroll
- Rate: $9.00 per $100
- Annual premium: $8,100
For most small Texas roofing businesses, expect to pay $2,500 to $10,000 per year for coverage.
What Drives Up Your Roofing Premium
Several factors push roofing premiums higher than other trades:
1. Fall Risk
Roofers work at heights. A single fall can result in catastrophic injury—spinal cord damage, traumatic brain injury, or death. Carriers price this risk into the rate.
2. Texas Heat
Heat-related illness claims spike between May and September. Extended exposure to extreme heat leads to dehydration, heat exhaustion, and heat stroke.
3. Subcontractor Classification
If you hire roofing subcontractors and misclassify them, you may be liable for their injuries. Texas Workforce Commission rules are strict.
4. Claims History
Even one serious claim can raise your experience modifier for years. A 1.2 modifier means paying 20% more than base rate.
5. Experience of Workers
New roofers have higher injury rates than experienced crews. Carriers factor in the average experience level of your workforce.
How the 3.8% Rate Decrease Affects Roofers
The Texas Department of Insurance approved a 3.8% overall decrease in workers’ compensation loss costs effective July 1, 2026.
For roofers, this means:
- If your premium was $10,000 last year, expect to pay around **$9,620** this year
- The decrease applies to new and renewal policies effective on or after July 1, 2026
- Individual carriers may adjust their rates differently
This continues a long trend. Texas workers’ comp rates have fallen 81% since 2003.
Does Texas Law Require Workers Comp for Roofers?
For most private roofing companies, no. Texas is the only state where private employers can legally opt out of workers’ compensation.
But there are critical exceptions:
1. Government Contracts Over $25,000
If you take a roofing job for a city, county, school district, or any government entity valued at $25,000 or more, you must provide workers’ comp for employees working on that project.
2. Public Project Subcontractors
Building and construction contractors on public projects must certify coverage in writing. This requirement flows down to every subcontractor.
3. General Contractor Requirements
Most commercial general contractors require subcontractors to show proof of workers’ comp before allowing them on site. Even if Texas law doesn’t force you, the market does.
4. Property Management Requirements
Commercial property managers and developers usually require certificates of insurance from roofing contractors. No coverage, no contract.
What Happens If a Roofer Gets Hurt Without Coverage
This is where the math becomes dangerous.
Without workers’ comp, your injured roofer can sue you directly. You cannot use these defenses:
- Contributory negligence — You can’t argue the roofer’s own carelessness caused the fall
- Assumption of risk — You can’t argue the roofer knew roofing was dangerous
- Fellow employee negligence — You can’t blame another crew member
What a roofer can recover:
- Medical expenses (past and future)
- Lost wages during recovery
- Lost future earning capacity
- Pain and suffering
- Mental anguish
- Physical impairment
- Disfigurement
A fall from a roof often results in catastrophic injuries. Spinal cord damage, traumatic brain injury, and multiple fractures can produce settlements or verdicts in the $500,000 to $5,000,000 range.
Even a moderate injury—a broken leg or wrist—can result in a $150,000 to $400,000 lawsuit.
The premium is a business expense. The lawsuit is a business-ending event.
How to Lower Your Roofing Workers Comp Premium
Several strategies can reduce your premium without sacrificing coverage:
1. Implement a Safety Program
Formal safety training, fall protection protocols, and regular toolbox talks can reduce claims. Many carriers offer 5% to 15% premium credits for certified safety programs.
2. Use the Right Classification
Make sure your office staff are classified as clerical, not roofing. Misclassification costs you money.
3. Consider a Higher Deductible
A higher deductible lowers your premium. Just make sure you can afford the deductible if a claim occurs.
4. Join a Safety Group
Texas allows employers to form safety groups for workers’ comp coverage. Group members may qualify for premium discounts.
5. Maintain a Clean Claims History
A clean record can earn you an experience modifier below 1.0, reducing your premium by 10% to 20%.
6. Use Return-to-Work Programs
The Texas Department of Insurance offers a return-to-work reimbursement program for small employers. You can get up to $5,000 for workplace modifications that help injured employees return to work.
7. Shop Multiple Carriers
Rates vary significantly between carriers. Get quotes from at least three Texas workers’ comp insurers.
When You Must Buy Coverage in Texas
While most private roofing companies can legally opt out, several situations require coverage:
- Government contracts over $25,000
- Building and construction contractors on public projects
- Public employers (if you do municipal roofing work)
- Motor carriers (if you operate trucks over public highways)
- Liquid propane gas dealers (if applicable to your business)
If you work in any of these categories, you must carry workers’ comp.
What Your Texas Roofing Workers Comp Covers
Your premium buys more than medical bills:
Medical Benefits: All reasonable and necessary medical care for work-related injuries.
Temporary Income Benefits: If a roofer misses more than 7 days of work, they receive a portion of lost wages.
Impairment Income Benefits: For permanent impairments from work injuries.
Death Benefits: Financial protection for surviving family members.
Employer’s Liability Coverage: Legal defense if you’re sued outside the workers’ comp system.
The maximum weekly benefit for 2027 is $1,314.32 for temporary income benefits.
The Non-Subscriber Trade-Off for Roofers
Texas gives you the choice to go without coverage. But choosing non-subscriber status for a roofing business is especially risky.
Why:
- Roofing injuries are typically more severe than other trades
- Falls from height often result in catastrophic injuries
- Jury sympathy for injured roofers is high
- Damages can include pain and suffering with no cap
One serious fall can result in a lawsuit that exceeds your annual revenue several times over.
FAQ
How much does workers comp cost for roofers in Texas?
Rates range from $5 to $15 per $100 of payroll, depending on classification and claims history. A small residential crew might pay $5,000 to $10,500 per year.
Is workers comp required for roofers in Texas?
No, not for most private employers. But government contracts over $25,000, public projects, and most commercial contracts require coverage.
What happens if a roofer gets hurt without workers comp in Texas?
The roofer can sue you directly. You cannot use contributory negligence, assumption of risk, or fellow employee negligence as defenses. Damages can include pain and suffering with no cap.
Are roofing subcontractors covered by my workers comp in Texas?
It depends on the working relationship. If you control how, when, and where they work, they may be considered employees. Texas Labor Code Section 406.145 allows joint agreements for independent contractor status.
How can I lower my roofing workers comp premium in Texas?
Implement a safety program, classify employees correctly, consider a higher deductible, join a safety group, maintain a clean claims history, and shop multiple carriers.
Are Texas workers comp rates going down in 2026?
Yes. TDI approved a 3.8% overall decrease in loss costs effective July 1, 2026. Individual carrier rates may vary.
What is the maximum weekly benefit for workers comp in Texas?
The maximum weekly benefit for 2027 is $1,314.32 for temporary income benefits.
The Bottom Line
Roofing is one of the most dangerous trades in Texas. Workers’ comp premiums reflect that risk—$5 to $15 per $100 of payroll is standard.
But the alternative is worse. Without coverage, a single fall can result in a lawsuit that exceeds your annual revenue. You lose every legal defense. Your roofer can sue for pain and suffering with no cap.
For most Texas roofing businesses, the math is simple. Pay the premium. Keep your legal defenses. Stay in business.
Related Articles:
- Does a Texas Plumber with 1 Helper Need Workers Comp?
- Texas Workers Comp Cost for Small Business (2026 Rates)
- Texas Workers Comp Exemptions: Who Can Legally Opt Out?
- What Happens If You Don’t Have Workers Comp in Texas?
Sources:
- Texas Department of Insurance: https://www.tdi.texas.gov
- Texas Workforce Commission: https://www.twc.texas.gov
- OSHA: https://www.osha.gov
- Texas Labor Code Section 406.033: https://statutes.capitol.texas.gov/Docs/LA/htm/LA.406.htm